All Categories
Featured

Low-Cost Health Insurance for US Veterans
Table of Contents
Premiums are normally lower for HMO plans, and there is normally no deductible or a low one. Some HMO plans, consisting of those used by Medical Mutual, do not require you to select a PCP or have a referral to see a specialist. For more HMO specifics, read our About HMO Plans article.
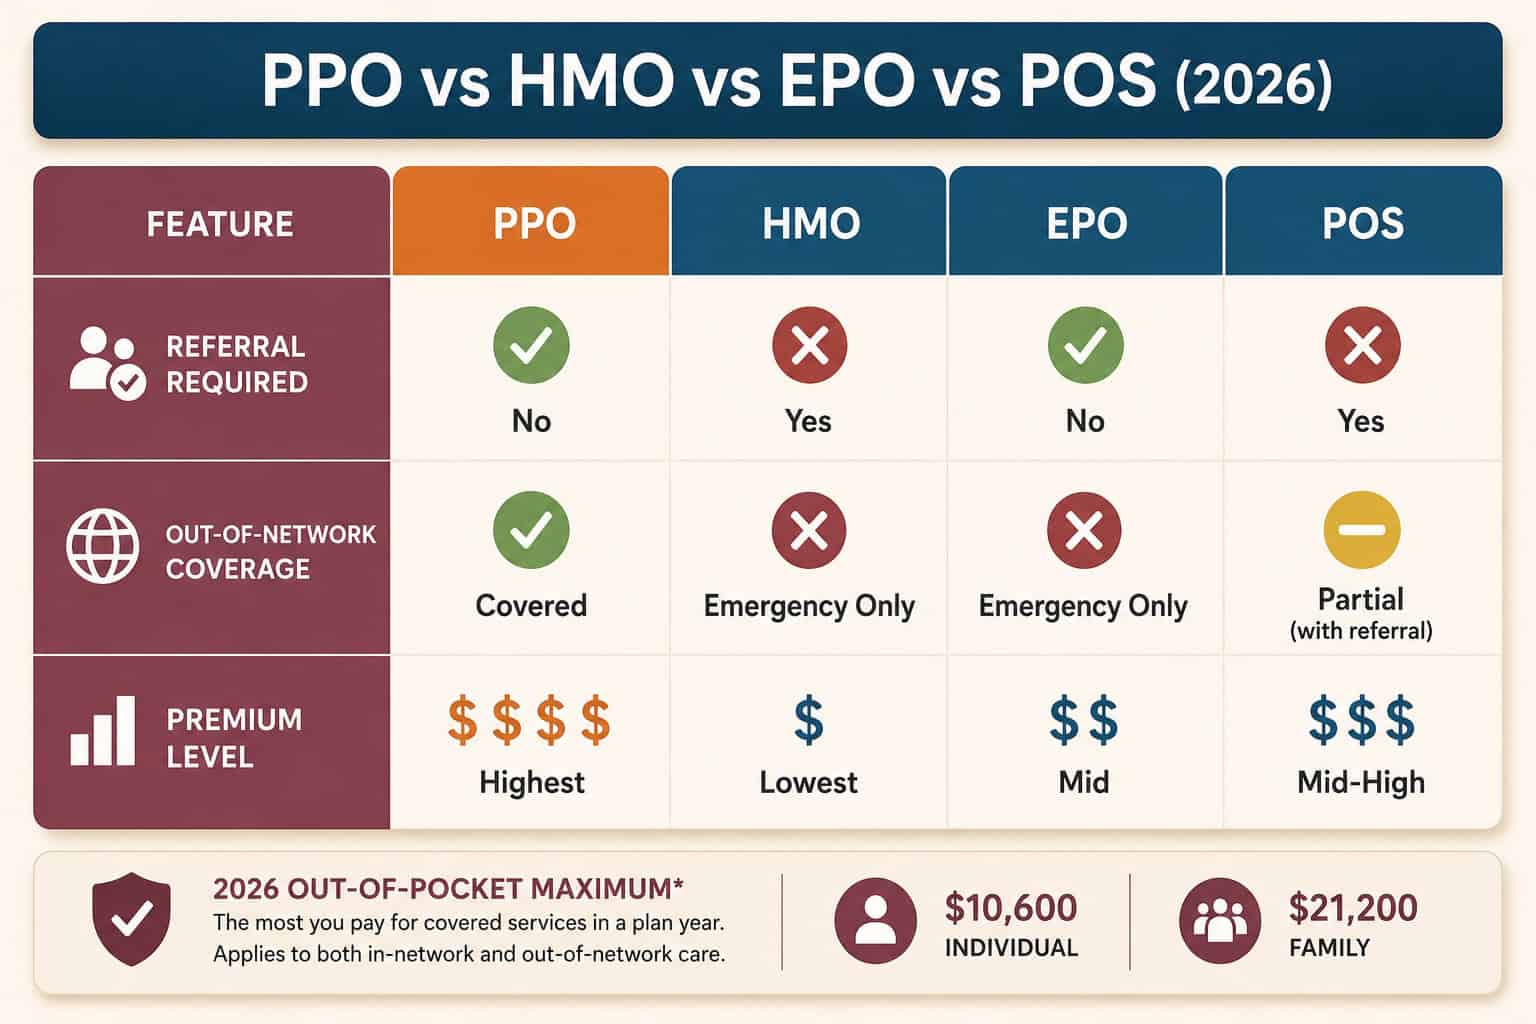
They likewise include a network of companies, but there are less restrictions on seeing non-network companies. In addition, your PPO insurance coverage will pay if you see a non-network company, although it might be at a lower rate. Here are some crucial functions: You can see the physician or specialist you 'd like without having to see a PCP.
Your advantages will be better if you stay in the PPO network. As discussed above, Distinctions in between HMO (Health Maintenance Company) and PPO (Preferred Supplier Organization) plans include network size, ability to see specialists, costs, and out-of-network protection.
Optimizing IUL Policy Benefits in Retirement
A specifying feature of HMO and PPO plans is that they both have networks. Networks are one method to lower health care costs network companies concur to offer discount rates in exchange for access to a health plan's members.
In basic, PPO networks tend to be more comprehensive, consisting of more physicians and health centers than HMO strategies, giving you more choice. Networks will differ from insurance provider to insurance company, and strategy to strategy, so it's best to research each strategy's network before you decide. Many HMOs will need you to select a main care physician, who will be the main point of contact for your treatment.
Expenses for experts will not be covered without a PCP referral. In contrast, PPOs tend not to need choice of a PCP, and you can typically see a professional without a referral, and still have these costs covered. For both PPO and HMO plans, your costs for care will be least expensive if you get it from in-network companies.
For HMOs, out-of-network services are generally not covered at all, except for emergency situations. PPOs vary from HMOs in that PPO strategies will usually supply some protection for these types of services, but coverage for in-network service providers will be far better. The additional coverage and versatility you obtain from a PPO suggests that PPO strategies will generally cost more than HMO plans.
Insurance in Oxnard CAAffordable Plan Choices for Veterans
This is the quantity of health care costs you need to pay before your strategy begins to cover your costs. Not all HMOs have deductibles, but when they do, they tend to be lower than PPO deductibles.
49% of covered workers had PPO strategies in the survey, while HMOs covered 16%. When it concerns your own health insurance option, it might sound like a cliche, however when selecting in between an HMO or PPO strategy, it is not necessarily about which is better, but which is finest for you.
If your monetary situation dictates that cost is essential, you might seriously think about going with an HMO plan. Normally speaking, expenses for HMO plans will be less. Premiums tend to be lower, and deductibles will also be lower, or may be absent totally. The trade-off will be versatility, however.
Insurance in Oxnard CAUnlike most HMO health insurance, you won't likely require to select a primary care physician, and you won't usually need a referral from that physician to see a professional. A PPO network will likely be larger, giving you a higher selection of in-network physicians, specialists, and facilities to select from.
Analyzing HMO Network Access and Monthly Costs
With HMOs, out-of-network protection will usually be limited to emergencies; non-emergency services are not normally covered at all. To assist you weigh the pros and cons detailed above, here's a quick summary of them: With any strategy, check the supplier network to see if your favored companies remain in the plan's network, since staying in-network will save you money.

You may find that the particular HMO plan you're thinking about contains your preferred providers, or at least enough of them to satisfy your requirements.

Latest Posts
Low-Cost Health Insurance for US Veterans
Top Medigap Plans for 2026

Exploring IUL Cash Value Potential